Stablecoins vs CBDCs vs tokenised deposits: the group chat
Sep 26, 2026 6 min read
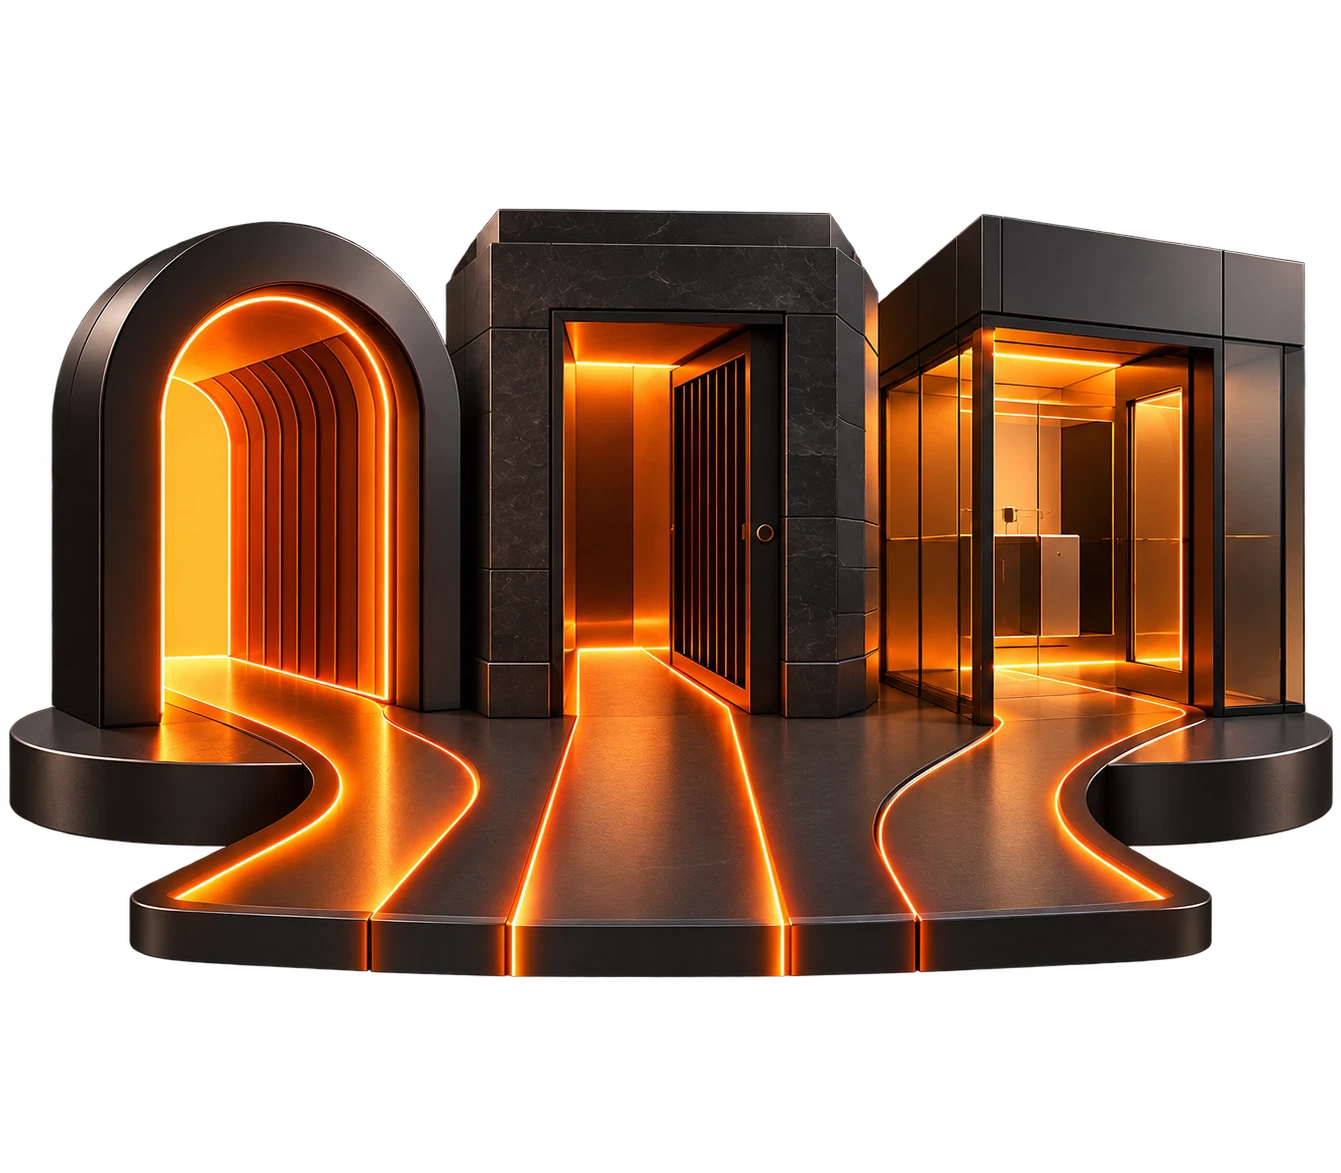
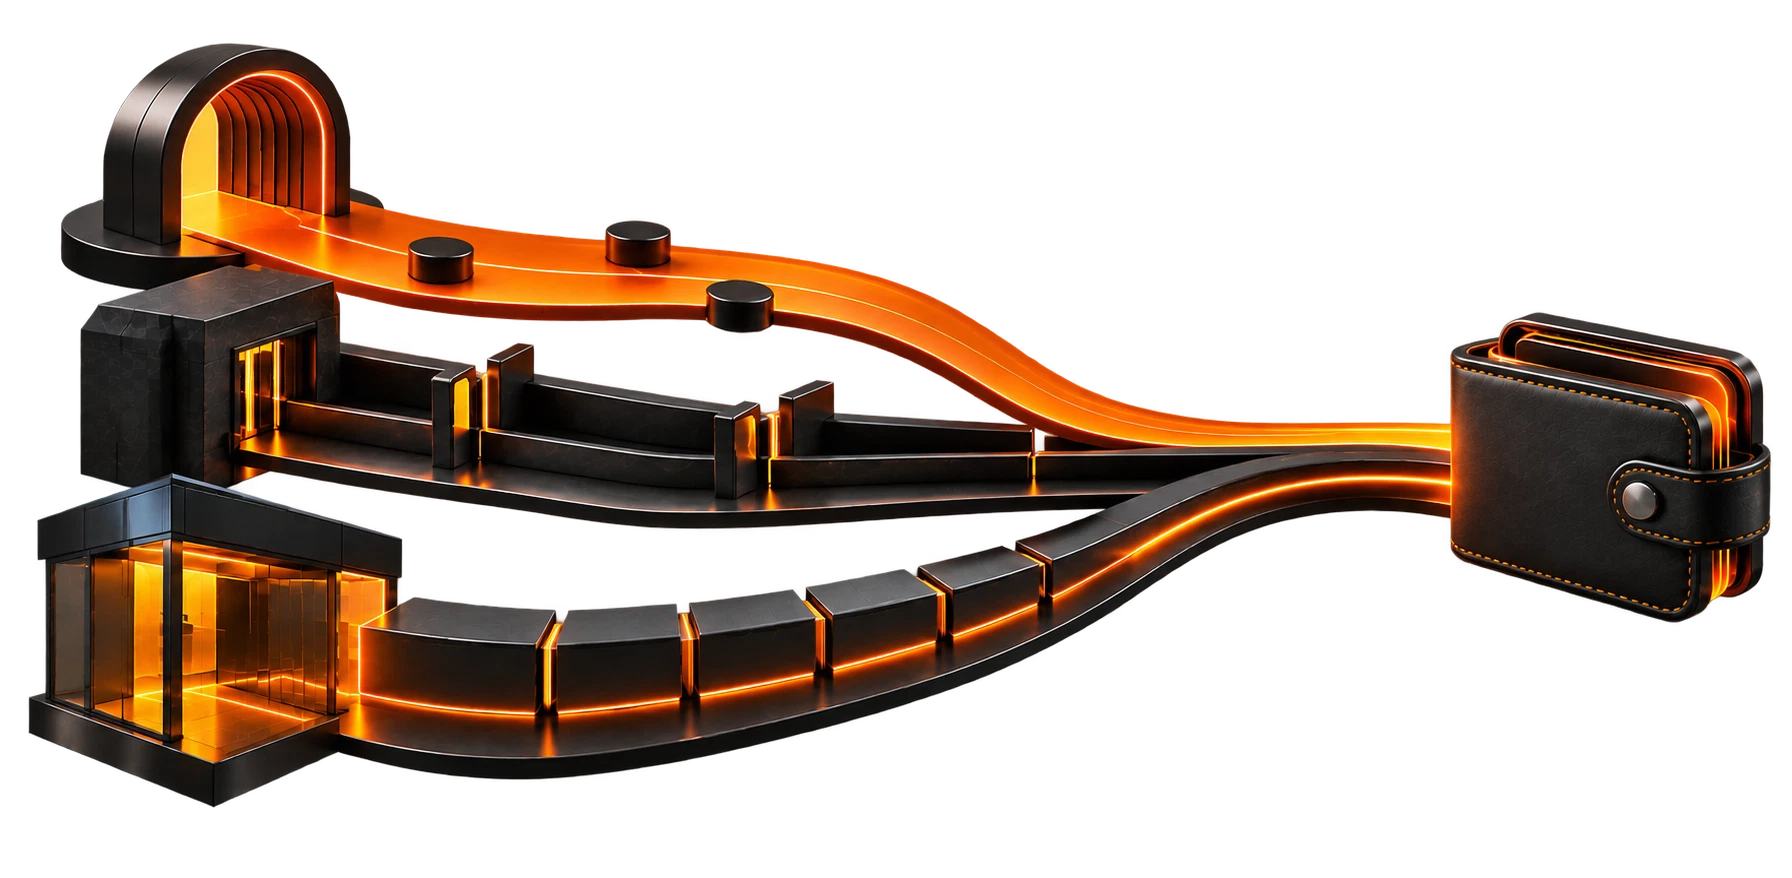
Three kinds of "digital money" are fighting for the same future. They look similar in a demo and completely different underneath. Meet the cast.
Stablecoins: the one that already shipped
Hundreds of billions in circulation, moving trillions a year, usable by anyone with a phone. Their strength is openness: any app, any country, any counterparty. Their weakness is trust in a private issuer, which is why regulation of reserves and redemption rights is the whole conversation right now, and why the big jurisdictions have spent the last two years writing rules for exactly that.
CBDCs: the one governments want
A central bank digital currency is cash, but digital, issued directly by the state. Pilots exist in dozens of countries; a handful are live. The pitch is safety and financial inclusion. The pushback is privacy: money that a central authority can see, and in theory program, makes people nervous, and adoption in most pilots has been quiet. The likely landing spot is wholesale (between banks) rather than the thing in your pocket.
Tokenised deposits: the banks' counter-offer
Take an ordinary bank deposit, represent it as a token on a ledger, and you get bank-grade money that settles instantly, 24/7, inside the existing regulatory perimeter. Big banks like this because it's their money, their customers and their rules. The catch is reach: a token
from one bank doesn't automatically work with another, so interoperability is the unsolved bit.
Who wins?
Probably nobody, in the sense that all three coexist: stablecoins for open, cross-border, consumer-to-anyone money; tokenised deposits for corporate and institutional flows; CBDCs mostly in the wholesale plumbing. The real winner is whichever apps can move between them without you noticing. That's the layer Kairo lives in.
TL;DR Stablecoins are open and already everywhere. CBDCs are state money with a privacy debate. Tokenised deposits are bank money that finally learned to settle on weekends. Expect all three; use the app that speaks all three.
All articles
See more
Stablecoins, explained like we're texting
A dollar that moves like a message. That's it. That's the tweet. But since you're here, the slightly longer version.
Sep 26, 20265 min read
USDT, USDC and friends: the tier list
Not all stablecoins are built the same. Some are backed by cash. Some are backed by vibes. Here's how to tell them apart before you hold one.
Sep 26, 20265 min read
One account. More ways to move.
Get started with Kairo.